Introduction
Managing money effectively requires more than earning a steady income or saving whatever remains at the end of each month. It involves developing a reliable strategy that turns financial decisions into consistent habits. As discussed in financial and business insights on TachCrunch.com, a structured financial planning process can help individuals and businesses understand their financial position, set achievable goals, control expenses, manage debt, and build long-term wealth. Instead of making financial decisions randomly, following an organized system can produce more measurable results.
This approach also makes it easier to prepare for unexpected expenses, changing market conditions, and important life events. Whether you are managing personal finances, planning for retirement, or improving a company’s financial performance, having a dependable system creates greater clarity and accountability. In this guide, we explore the essential steps, tools, benefits, and strategies needed to develop an effective financial planning process that adapts as your financial circumstances evolve.
1. What Is a Repeatable Financial Planning Process?
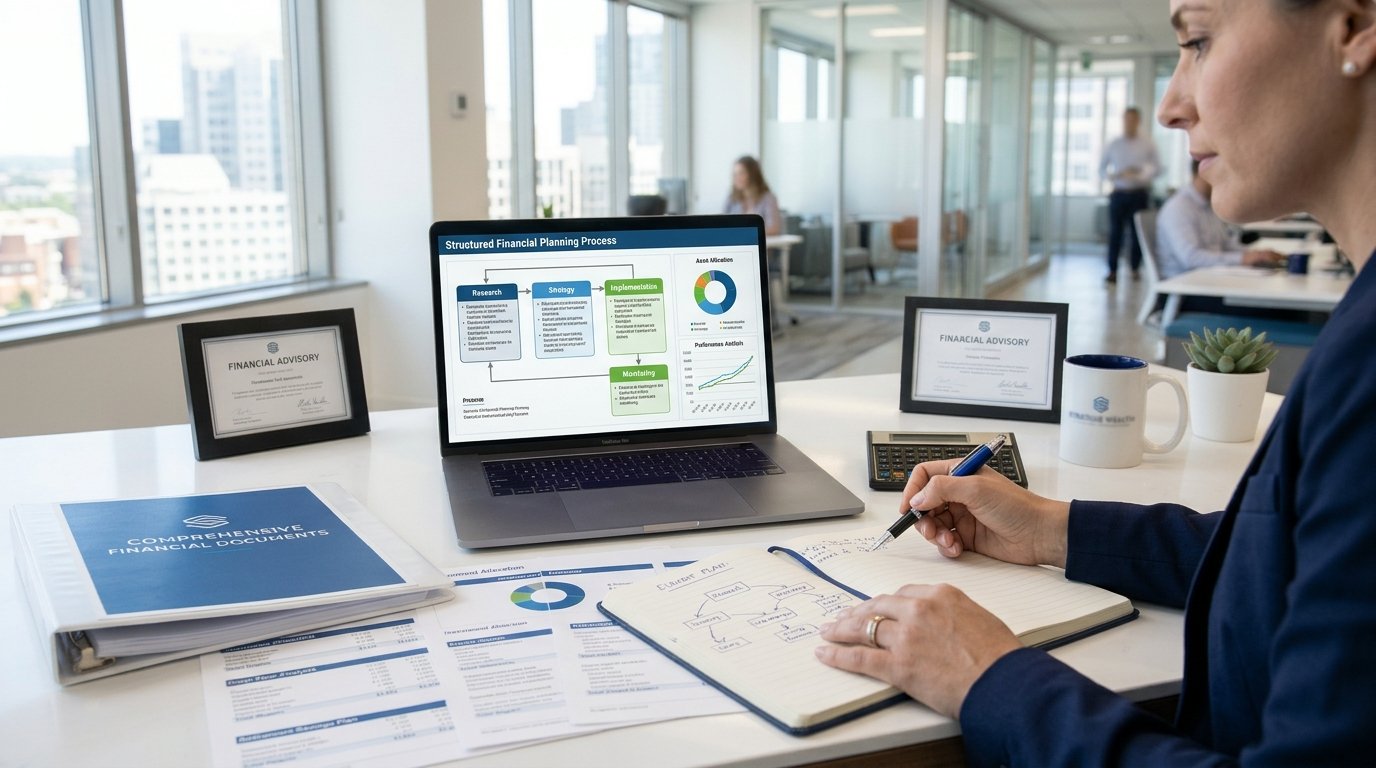
A repeatable monetary making plans procedure is an prepared device for comparing financial occasions, organising desires, allocating resources, monitoring performance, and making adjustments over the years. It gives a consistent structure for economic selections in place of relying on occasional exams or short-term reactions.
The phrase “repeatable” is especially vital. A monetary plan must not be created and forgotten as soon as it is made. It must follow a cycle that may be executed frequently, evaluated objectively, and progressed each time occasions exchange.
For instance, a character might review monthly income, categorize charges, transfer a part of income into financial savings, pay down super debt, and examine investment contributions. Repeating these steps creates an economic habit that helps long-term stability.
Businesses can apply the same principle by means of reviewing revenue, forecasting expenses, tracking cash flow, comparing profitability, and adjusting budgets. The particular monetary measurements can also vary, but the underlying method remains similar.
A successful repeatable process generally includes five foundations:
- Consistency: Financial activities follow a predictable schedule.
- Clarity: Every financial intention has a described motive.
- Accountability: Progress is measured in opposition to set goals.
- Flexibility: Financial decisions can alternate when circumstances require it.
- Continuous improvement: Regular reviews identify opportunities to improve outcomes.
The objective is not to predict every financial challenge. It is to establish a system that makes financial decisions more organized, informed, and manageable.
2. Why Is a Repeatable Financial Planning Process Important?
Financial circumstances can change quickly. Income may growth or decrease, household costs may additionally upward thrust, interest rates may additionally range, and surprising economic obligations can appear. Without a established technique, these adjustments could make it hard to hold monetary balance.
A repeatable financial planning manner gives path and allows save you short-term selections from interfering with long-time period goals.
Staying informed about business developments, economic changes, and financial trends can also support better financial decisions. Platforms like GoodsNewsNetwork.com provide news and updates that help readers stay connected with developments affecting businesses and the wider economy.
Creates Financial Clarity
Understanding wherein money comes from and wherein it is going is the foundation of monetary control. A constant planning system affords visibility into income, spending patterns, fixed responsibilities, financial savings, and investments.
These facts allow become aware of economic troubles before they come to be difficult to manage.
Encourages Consistent Saving
Saving will become less difficult when it’s treated as a planned financial obligation instead of an occasional activity. A repeatable manner establishes financial savings targets and encourages regular contributions.
For example, someone who robotically transfers a set percentage of monthly profits into savings can steadily build economic reserves without making the selection from scratch every month.
Improves Financial Decision-Making
A structured monetary plan offers a reference factor for comparing purchases, investments, borrowing selections, and most importantly, costs.
Instead of creating choices primarily based absolutely on feelings or instantaneous needs, individuals can remember how each choice impacts their hooked up financial priorities.
Supports Better Risk Management
Financial planning also involves getting ready for uncertainty. Emergency financial savings, suitable insurance, debt control, and funding diversification can help lessen exposure to surprising monetary problems.
Makes Progress Measurable
A repeatable technique creates opportunities to compare overall performance through the years. You can decide whether or not financial savings are increasing, debt is declining, charges are managed, and financial goals continue to be possible. This measurement encourages duty and facilitates perceive regions that want improvement.
3. Eight Essential Steps to Create a Repeatable Financial Planning Process
Developing a reliable economic planning device does now not require complicated monetary fashions. The best method is initially primary financial data and build a ordinary round measurable sports.
Step 1: Evaluate Your Current Financial Situation
Before organising financial goals, understand your existing monetary position. Planning without accurate information can result in unrealistic expectations and useless decisions.
Start through amassing facts approximately your financial sports.
Review your income: Calculate your ordinary monthly earnings after taxes and mandatory deductions. Include salaries, business profits, freelance bills, rental profits, and other reliable resources.
Calculate your prices: Examine housing prices, transportation, groceries, utilities, subscriptions, healthcare, education, and discretionary purchases.
Identify your property: List financial savings, debts, investments, retirement price range, property, cars, and other valuable assets.
Review your liabilities: Record credit score card balances, personal loans, mortgages, schooling loans, and different high-quality obligations.
You can calculate your net worth using a simple formula:
Net Worth = Total Assets − Total Liabilities
For instance, suppose a person owns assets really worth $75,000 and has extremely good liabilities of $25,000. Their predicted net worth is $50,000.
This calculation presents a starting line for measuring economic progress.
It is likewise useful to calculate your monthly cash flow:
Monthly Cash Flow = Monthly Income − Monthly Expenses
A high-quality result approach earnings exceeds fees, even as a poor end result suggests that spending exceeds to be had profits.
Reviewing those figures often allows you to understand whether your current financial behavior assists your long-term targets.
Step 2: Establish Clear and Measurable Financial Goals
Once you understand your economic role, discover what you want to reap. Financial goals offer direction and help decide how available resources should be allocated.
Avoid indistinct objectives consisting of wanting to become rich or keep extra cash. Instead, establish precise targets with sensible cut-off dates.
Divide your goals into three classes:
Short-time period goals: These commonly cover the subsequent one year. Examples encompass paying off a credit card, improving credit score stability, saving for a vacation, or constructing an initial emergency fund.
Medium-time period dreams: These generally require one to 5 years. Examples encompass shopping for a vehicle, investment education, or saving for a down payment.
Long-time period goals: These increase past five years and can encompass retirement planning, purchasing belongings, constructing an funding portfolio, or accomplishing monetary independence.
A useful method for setting goals is the SMART framework:
- Specific: Clearly define the financial outcome.
- Measurable: Assign a monetary target.
- Achievable: Consider your income and existing obligations.
- Relevant: Connect the goal to your broader priorities.
- Time-bound: Establish a realistic completion date.
For example, instead of saying, “I want to save money,” create a target such as saving $6,000 within 12 months.
This means setting aside approximately $500 each month, assuming there are no additional contributions or investment returns.
Breaking large objectives into smaller monthly targets makes financial goals easier to manage and measure.
Step 3: Develop a Practical Budget
A budget converts economic dreams into ordinary spending choices. It establishes how much cash must be allotted to essential expenses, personal spending, debt bills, and savings.
Start by organizing prices into categories.
Fixed expenses: These consist of rent, mortgage payments, insurance charges, and ordinary loan installments.
Variable charges: These consist of groceries, transportation, utilities, healthcare, and different prices that can alternate month-to-month.
Discretionary prices: These include amusement, eating out, buying, subscriptions, and nonessential purchases.
After categorizing prices, examine total spending with month-to-month earnings. Identify areas wherein modifications could create additional savings.
One popular budgeting method is the 50/30/20 rule:
- 50% of income for needs.
- 30% for wants.
- 20% for savings and debt repayment.
This framework is a starting point in choosing a strict requirement. People with excessive housing fees, giant debt, or lower earning may additionally moreover want distinct allocations.
The most important principle is to create a price range that reflects your real financial circumstances.
Review your spending at the end of each month. If certain classes continually exceed their limits, investigate why and alter your price range because of this.
A practical budget range should support mindful financial conduct without making everyday lifestyles unnecessarily restrictive.
Step 4: Build an Emergency Fund
Unexpected expenses can disrupt even a cautiously prepared financial plan. Medical bills, automobile maintenance, brief unemployment, and pressing household costs can create economic strain.
An emergency fund provides handy money for those situations without requiring additional borrowing or promoting long-term investments at an inconvenient time.
A common starting target is to store enough to cover three to six months of crucial living expenses. The appropriate amount depends on income balance, family duties, insurance, and personal situations.
For example, if essential monthly expenses total $2,000, an emergency fund covering three to six months would range from $6,000 to $12,000.
You do not need to build this amount immediately.
Start with a smaller milestone, such as saving $500 or $1,000. Then gradually increase contributions until you reach your target.
Consider maintaining emergency savings in an available, low-risk account that is free from regular spending cash.
Most importantly, set up clear policies for the use of the fund. It should cover true surprising wishes instead of routine purchases or planned amusement charges.
Step 5: Create a Debt Management Strategy
Debt can reduce economic flexibility due to the fact interest and compensation duties eat money that would otherwise help financial savings and investments.
A repeatable money-management plan system has to consist of a clear approach for coping with notable debt.
Begin by listing each debt, consisting of:
- Outstanding stability.
- Interest fee.
- Minimum monthly payment.
- Repayment deadline.
- Any extra costs or consequences.
Once the information is organized, choose a repayment strategy.
Debt avalanche method: Focus additional payments on the debt with the highest interest rate whilst preserving minimum payments on different debts. This method can reduce general interest expenses.
Debt snowball technique: Pay off the smallest balance first at the same time as preserving minimum payments on other money owed. This method can offer motivational progress through smaller early victories.
For instance, a person with three credit card balances can also select to prioritize the card charging the very best interest rate. Once that balance is removed, the amount previously allocated to it could be directed toward the next debt.
Avoid collecting useless new debt whilst following your compensation plan.
It is also important to differentiate among debt that supports a carefully evaluated long-term objective and pricey consumer debt that creates ongoing financial strain.
Review interest quotes and reimbursement terms periodically, and remember professional guidance whilst debt responsibilities end up tough to manipulate.
Step 6: Develop an Investment and Savings Strategy
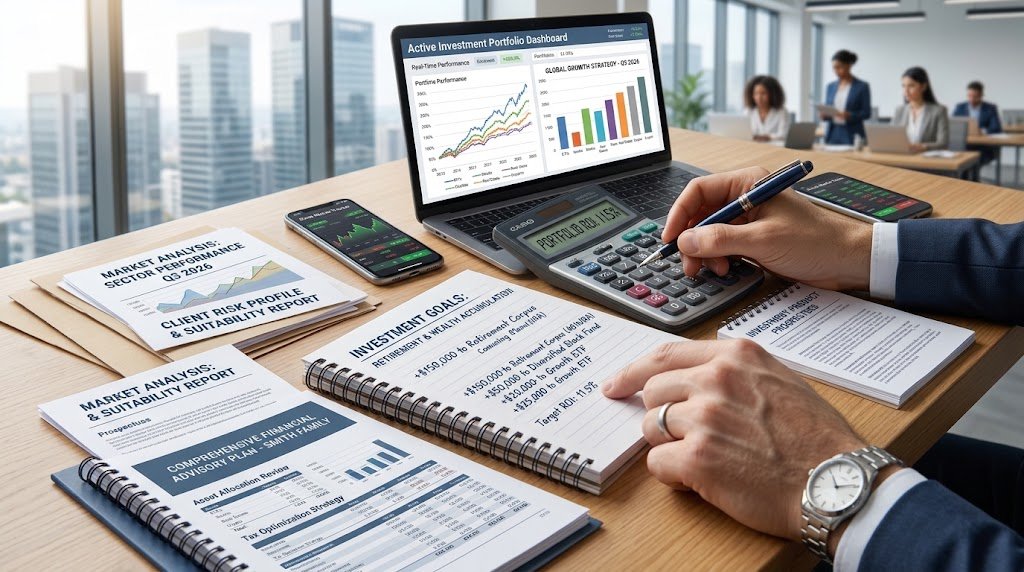
Saving and making an investment serve one-of-a-kind functions inside a monetary plan.
Savings typically provide liquidity and balance for short-term desires, while investing can assist in building wealth over longer durations. A balanced strategy considers the time horizon, economic targets, risk tolerance, and available resources.
Start by identifying the motive of each investment.
For instance:
- Short-term goals may require on-hand financial savings and lower-risk monetary products.
- Medium-term dreams may additionally contain a mixture of savings and carefully selected investments.
- Long-term goals may allow a different funding portfolio designed for growth.
Diversification is an important investment precept. Instead of concentrating all your cash in a single organization, asset, or market area, consider spreading investments throughout suitable asset classes.
Depending on your situation, those may also include stocks, bonds, mutual funds, exchange-traded funds, or different regulated funding products.
Understand the dangers, fees, liquidity regulations, and tax implications before making an investment.
Your risk tolerance also matters. Someone who can’t effortlessly take care of significant marketplace fluctuations may also need a specific investment allocation from a person with a longer investment horizon and greater capability for risk.
Avoid making funding decisions primarily based entirely on social media guidelines, market exhilaration, or short-term price moves.
A repeatable funding approach focuses on steady contributions, appropriate diversification, periodic critiques, and alignment with long-term goals.
Step 7: Monitor Financial Performance
Creating an economic plan is only the start. Regular tracking helps determine whether your method is generating the expected consequences. Establish a monthly monetary assessment to evaluate vital measurements.
These may additionally include:
- Monthly earnings and prices.
- Savings contributions.
- Emergency fund balance.
- Outstanding debt.
- Investment contributions.
- Changes in net worth.
- Progress towards economic dreams.
Compare real performance with your original finances and monetary objectives.
For instance, if you planned to save $400 month-to-month but consistently saved only $250, check out the difference. Your prices may have increased, your original goal may be unrealistic, or your spending categories may additionally need adjustment.
The purpose of monitoring isn’t to criticize each monetary mistake. It is to apprehend what is going on and make knowledgeable upgrades.
An easy spreadsheet can be enough for tracking these measurements. More superior budgeting programs and monetary dashboards can also assist prepare economic facts.
Consistent monitoring turns economic making plans into an active management method instead of a report that turns into old.
Step 8: Review and Improve the Financial Plan
Financial plans should evolve as income, responsibilities, financial situations, and personal priorities change.
An evaluation timetable helps ensure that your financial strategy remains applicable.
Monthly reviews: Check spending, savings, bills, debt payments, and cash flow.
Quarterly evaluations: Evaluate development in the direction of financial goals, evaluation investment allocations, and pick out widespread adjustments in monetary overall performance.
Annual evaluations: Reassess lengthy-time period goals, retirement contributions, insurance wishes, tax concerns, and ordinary financial role.
You should also evaluation your economic plan after important lifestyles activities, consisting of marriage, having kids, changing jobs, starting a commercial enterprise, purchasing belongings, or experiencing a widespread profits change.
For organizations, important evaluation triggers may include changes in revenue, running costs, staffing requirements, client demand, and expansion plans.
The goal is to preserve consistency without becoming rigid.
A successful financial planning system provides a strong framework whilst allowing personnel selections to conform to new records.
Conclusion
A repeatable financial planning system is essential for everyone who desires to control cash successfully and construct long-term financial balance. By comparing your financial position, organising measurable goals, creating a realistic budget, managing debt, and growing the best financial savings and investment approach, you may make better financial decisions.
However, developing a plan is the simplest start. Consistent tracking, normal opinions, and timely modifications are similarly critical for keeping development. Financial situations will alternate, but a dependent method facilitates you reply with extra confidence and control.
Whether you are dealing with personal price range or overseeing commercial enterprise sources, developing dependable economic behavior can improve duty and reduce needless economic uncertainty.
Start with small, achievable steps, track your progress, and enhance your method over time. Remember, lasting economic fulfillment hardly ever comes from one foremost selection; it develops via constant actions, knowledgeable selections, and a commitment to continuous monetary improvement.
(FAQs)
1. What Is a Repeatable Financial Planning Process?
A repeatable financial planning procedure is a dependable method for coping with money through consistent activities which includes budgeting, saving, debt control, investing, and reviewing financial performance. It lets in individuals and organizations to make knowledgeable choices, measure development, and adjust financial strategies as instances alternate. Rather than developing a economic plan as soon as, this method entails following an ongoing cycle of assessment, implementation, monitoring, and improvement.
2. How Often Should You Review Your Financial Plan?
You should overview your economic plan as a minimum once a month to screen earnings, prices, financial savings, and debt payments. A more designated quarterly evaluation can assist in comparing funding performance and progress towards financial goals. An annual evaluation is likewise crucial for updating long-term objectives, retirement strategies, coverage requirements, and monetary priorities. Major life events or big profit adjustments should prompt an additional assessment.
3. What Is the First Step in Creating a Financial Planning Process?
The first step is evaluating your current financial scenario. Calculate your earnings, monthly fees, savings, property, and first-rate liabilities to understand your financial situation. This evaluation establishes a sensible place to begin and enables discover regions that require development. Once you understand your current situation, you can set up measurable goals, broaden a budget, and create a practical method for achieving long-term financial stability.
Pingback: Set Active Lindsey Carter Entrepreneurship || Read Now!