Introduction
MacBook BNPL can be worthwhile if you need a reliable PC, have strong cash flow, and qualify for a clear plan with low payments.
It’s much less suitable if your profits are unpredictable, you already have many installment commitments, or the purchase would leave you unable to cover critical expenses.
For an expert running with demanding creative packages and exploring the latest technology, a MacBook Pro may justify its higher price if its overall performance suits the workload.
In both cases, the key is to prioritize practical needs over simply buying the most expensive gadget available. The proper financing plan should make an important purchase easier to manage. It should not make a needless purchase seem inexpensive just because the charge is split into smaller payments.
What Is MacBook BNPL?
MacBook BNPL is a price arrangement that lets in an eligible patron to purchase a MacBook straight away and pay for it in installments as opposed to paying the complete quantity at checkout.
Depending on the provider, compensation might manifest over several weeks or through monthly installments lasting several months or longer. Some plans charge no interest while you meet their conditions. Others charge interest or fees.
For instance, consider a MacBook costing $1,200. A hypothetical 12-month installment plan with 0 interest would require payments of $ 100 per month, aside from any extra fees.
That sounds more possible than paying $1,2 hundred in one payment. However, you continue to owe the whole buy price. BNPL changes the timing of your bills, not the actual fee of the computer.
According to the Consumer Financial Protection Bureau’s BNPL steering, many, though not all, BNPL loans divide a purchase into 4 or fewer bills, while different installment products can also use exceptional reimbursement structures.
The vital difference is that BNPL is a form of credit, not a discount.
How Does Buy Now, Pay Later for a MacBook Work?
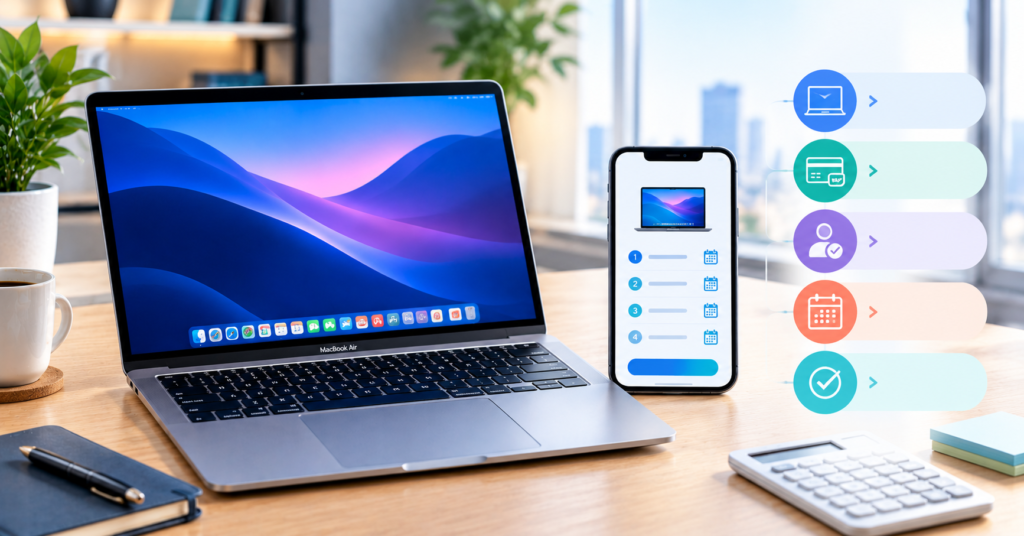
The procedure is normally straightforward, although the precise steps depend upon the store and financing provider.
1. Choose your MacBook
Start by using evaluation to be had, models. A MacBook Air may additionally match students, normal customers, and plenty of specialists. A MacBook Pro may also be better for intensive video editing, software development, and other demanding workloads.
Consider the memory, storage, processor, display length, and anticipated lifespan of the machine before focusing on the month-to-month price.
2. Select an installment choice
Add the MacBook to your cart and evaluate the charge strategies offered at checkout. Depending on your region and the retailer, you may find a BNPL company, a committed financing plan, or a credit card installment alternative.
Not every company finances every Apple product. Some have purchase limits or require a minimum transaction amount.
3. Complete the eligibility test
The provider may additionally ask for identification info, income information, and payment account information. Approval can rely on your place, age, credit score profile, economic circumstances, and the company’s regulations.
Being authorized for one BNPL buy does not guarantee approval for a MacBook. An extra pricey purchase can be assessed otherwise.
4. Review the reimbursement settlement
Before accepting the offer, take a look at the deposit, installment amount, repayment dates, hobby fee, expenses, and total amount payable.
A fee plan marketed as hobby-loose may nevertheless have other conditions. Read the settlement in preference to counting on a promotional headline.
5. Make payments on schedule
Once the purchase is permitted, comply with the issuer’s reimbursement schedule. Set reminders or computerized payments where appropriate, and preserve sufficient cash within the related account.
Your new MacBook ought to assist you in getting payments executed. It has to not end up being the reason you spend every payday negotiating with your banking app.
Where Can You Buy a MacBook With BNPL?
The best place to start is the official Apple Store in the United States, followed by reputable electronics retailers and authorized resellers that clearly disclose their financing terms.
Availability varies with the aid of marketplace, so test the modern-day provider in place of assuming an issuer operates anywhere.
Apple’s official financing options
Apple gives distinct price and financing arrangements in different countries.
For instance, Apple’s US financing web page describes Apple Card Monthly Installments for eligible Mac purchases. This is a particular US presenting, not a normal financing opportunity to be had to every Apple purchaser.
Apple’s Canadian financing page lists financing through Affirm, with the posted phrases varying by product. This highlights why buyers should check Apple’s website for their own country before making assumptions about interest rates or repayment terms.
Apple’s UK financing information describes financing arrangements available to eligible clients inside the United Kingdom.
These packages can vary. Check the current annual percentage rate (APR), charges, and eligibility requirements at checkout.
BNPL providers such as Klarna and Affirm
Some outlets provide installment plans through 1/3-celebration carriers, including Klarna or Affirm. The actual options depend on the service provider, the purchase, and the consumer’s eligibility.
Do not assume that seeing an issuer’s brand on one website means you could use it to buy a MacBook from every different retailer.
Start with the seller’s checkout web page and verify that the MacBook itself qualifies for the plan. Then read the provider’s agreement, which includes its policies for refunds, past-due bills, and credit score reporting.
Electronics retailers and authorized resellers
Retailers may provide their very own financing packages or accomplice with lending organizations.
Compare the entire payable amount, not simply the marketed month-to-month charge. Also confirm that the seller is legitimate, the tool is actual, and the warranty and return policy are really explained.
A suspiciously cheap MacBook with an unbelievably clean financing offer merits more scrutiny. A good buy is most effective as a bargain whilst the pc really arrives.
MacBook BNPL vs. Credit Cards vs. Personal Loans
Different pricing methods match exclusive circumstances. Here is how the primary alternatives are examined.
| Payment method | Potential advantage | Main consideration |
| BNPL | Smaller scheduled bills | Fees, reimbursement situations, and overlooked payment outcomes |
| Promotional credit card financing | May offer interest-unfastened installments to eligible cardholders | Promotional phrases and eligibility necessities |
| Standard credit score card | Convenient and broadly applicable | Interest can be collected if you deliver stability |
| Personal mortgage | May provide a predictable repayment agenda | Interest, expenses, and credit score approval |
| Saving before buying | Avoids borrowing prices | You should wait until you have sufficient cash |
The best alternative relies on the total price, repayment period, and your ability to make payments reliably.
For instance, a genuine zero-interest plan can be less expensive than a personal loan with interest. But if a credit card’s promotional duration expires before you pay off the balance, the evaluation might also change drastically.
For more insights into technology, business, and consumer trends, visit Goods News Network.
How Much Does a MacBook Cost Per Month?
Your month-to-month fee depends on the MacBook’s purchase price, the down payment, the compensation period, and any hobbies or expenses.
The following examples are illustrations, not live quotes or modern-day MacBook costs.
| Example purchase price | Settlement term | Monthly fee at 0% interest |
| $800 | 8 months | $100 |
| $1,200 | 12 months | $100 |
| $1,800 | 18 months | $100 |
| $2,400 | 24 months | $100 |
These calculations assume the whole purchase fee is financed equally without interest, fees, or upfront payment.
Example: Financing a MacBook Air
Suppose you want a computer for college assignments, surfing, and freelance work. You find an appropriate MacBook Air for $1,200 and qualify for a 12-month zero-interest plan.
Your fee could be $100, consistent with the month.
Before accepting, ask yourself 3 questions:
- Can I readily pay $a hundred each month after hire, meals, transport, and other essentials?
- Will I nevertheless have emergency financial savings after protecting my other commitments?
- Would a less steeply priced model meet my wishes just as well?
If the answers look good, financing might be affordable. If the fee depends on receiving a freelance client every month without fail, consider a less expensive version or saving for a bigger deposit first.
What happens when interest is added?
Suppose you finance $1,200 for one year at a hypothetical 12% annual interest rate, calculated on a declining balance with monthly payments.
The price would be approximately $106.62 in keeping with the month, with general payments of about $1,279.Forty-four, excluding costs.
That is roughly $seventy nine.44 greater than the actual price. Actual figures rely on the lender’s calculation approach, compounding, prices, and compensation phrases.
This is why the advertised installment is only a part of the story. The overall amount payable tells you what the MacBook genuinely costs beneath the financing agreement.
Benefits of Buying a MacBook with BNPL
Keep more cash available upfront.
Paying in installments can keep some of your available cash for crucial fees and unexpected bills. This may be beneficial while a pc is important for painting or training. However, maintaining coins only helps when the destination bills stay less expensive.
Start working quicker
An appropriate laptop can help a freelancer edit movies, manipulate websites, write articles, develop software, or attend online classes. If the MacBook is certainly necessary for income, profits, or completing coursework, spreading the cost can be sensible. Still, do now not count on that buying a extra pricey model will routinely boom your profits.
Make prices easier to plan
Fixed installments can make budgeting more predictable when the agreement has clear terms and no unexpected prices. You can encompass the month-to-month payment to your price range alongside subscriptions, utilities, and different habitual expenses.
Access an appropriate version without paying the whole thing at once
A carefully selected installment plan may also assist you in acquiring a computer that meets your real requirements. The key is choosing the least luxurious model that simply handles your workload instead of financing extra specifications you may hardly ever use.
Keep more cash available upfront.
Paying in installments can preserve some of your available cash for essential expenses and unexpected bills. This can be helpful when a laptop is necessary for work or education. However, preserving cash only helps when the future payments remain affordable.
Start working sooner
A suitable laptop can help a freelancer edit videos, manage websites, write articles, develop software, or attend online classes. If the MacBook is genuinely necessary for earning income or completing coursework, spreading the cost may be practical. Still, do not assume that buying a more expensive model will automatically increase your income.
Make expenses easier to plan
Fixed installments can make budgeting more predictable when the agreement has clear terms and no unexpected charges. You can include the monthly payment in your budget alongside subscriptions, utilities, and other recurring costs.
Access a suitable model without paying everything immediately
A carefully chosen installment plan may help you obtain a laptop that meets your actual requirements. The key is choosing the least expensive model that comfortably handles your workload rather than financing extra specifications you will rarely use.
How to Choose the Right MacBook BNPL Plan
Use this realistic checklist before committing to a buy.
- Set a sensible budget. Decide how much you can find the money for every month after vital expenses and existing debt payments.
- Compare the overall fee. Include interest, costs, deposits, and any required extra purchases.
- Check the repayment length. Make sure the time period suits your price range and does not make it unnecessarily longer.
- Read the late-payment policy. Understand what takes place in case your charge is behind schedule or declined.
- Check returns and warranty coverage. Confirm the vendor’s policies before you pay.
- Verify the issuer. Use a good retailer and examine the real financing agreement.
- Consider options. Compare refurbished gadgets, previous-era MacBooks, student discounts where eligible, and saving for a larger upfront fee.
A useful rule is to choose a monthly charge that remains possible even throughout a less worthwhile month. Freelancers and small-business proprietors ought to be mainly cautious about relying on earnings that have not yet arrived.
Is MacBook BNPL worth It?
MacBook BNPL can be worthwhile if you need a reliable pc, have strong cash flow, and qualify for an obvious plan with low-priced payments.
It can be much less suitable if your profits are unpredictable, you have already got numerous installment commitments, or the purchase would leave you unable to cover critical charges.
For a student, a lower-cost MacBook Air may additionally offer everything necessary for assignments and research. For an expert running with annoying creative packages, a MacBook Pro may justify its higher price if its overall performance suits the workload.
In both cases, the key is to prioritize practical needs over simply choosing the most expensive device available. The proper financing plan should make an important purchase easier to manage. It should not make a needless purchase seem inexpensive just because the charge is split into smaller payments.